
04: Body care is being bought like skincare and fragrance

Published October 2026 · Amazon data to September 30, 2026
The short version:
Amazon search for four body care themes grew 39% to 79% over the last year: skincare actives on the body, body wash as treatment, body care sold as fragrance and hair removal at home.
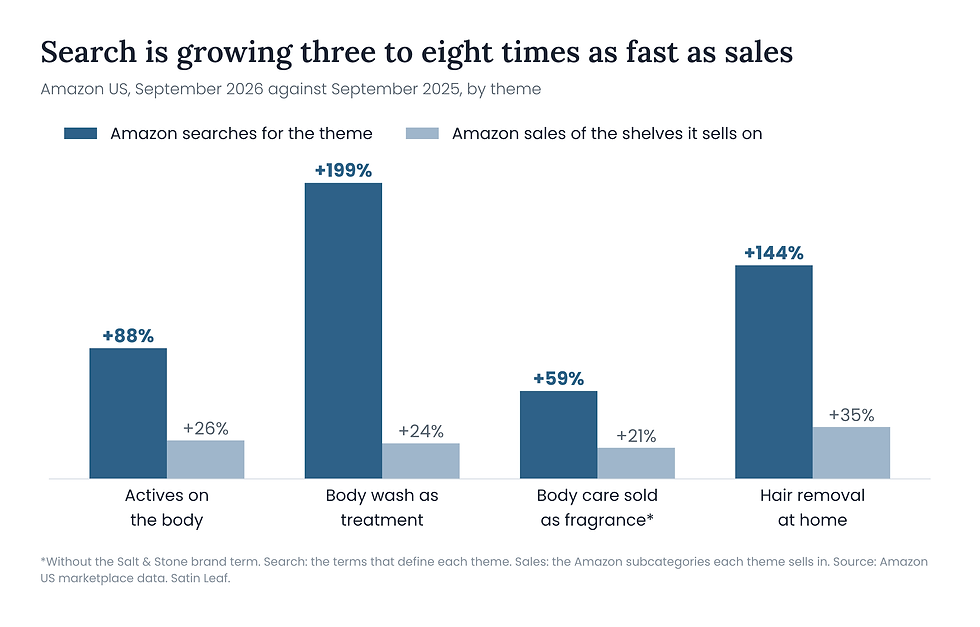
In September, search for each theme grew three to eight times as fast as the sales of the shelves it sells on.
Shoppers are buying body care for its actives and for its scent, the way they buy face care and fragrance.
Funds and strategics have done nine body care deals since 2025. Funds paid about 3x sales; strategics have paid 3.4x to 5.5x.
We name 30 brands to watch, from $0.2 million to $102 million on Amazon.
Body care used to be a commodity aisle. It is now one of the fastest parts of beauty: in the first half of 2026, body and sun care led US prestige beauty at +16%, against +7% for prestige overall. On Amazon the growth sits in four places.
Four places the growth is
Skincare actives move to the body. Retinol body lotion search rose 113% and urea cream 72%. Much of urea search is for feet and heels; take it out and the theme still grew 72%. Firming lotion rose only 9%, and the brands built on older claims are shrinking on Amazon: Crepe Erase is down 12% and Bio-Oil 7%. Skinfix, an eczema and bumpy-skin brand, grew 91%, and OneSkin, a peptide lotion sold mostly by subscription, doubled.
Body wash becomes a treatment. Kojic acid body wash search doubled, brightening washes rose 87% and body toner nearly quadrupled. medicube set the format and entered more than 1,500 Target stores in April. The older format is losing: Kojie San, a kojic soap brand, is down 22% on Amazon. CYKLAR, at Sephora since early 2026, grew from almost nothing to $20.5 million on Amazon.
Body care sold as fragrance. Deodorant, body mist and men's body butter are bought for the scent. One brand drives most of the search: "Salt & Stone deodorant" rose more than five times. Without that term the theme grew 39%; with it, 161%. Plain "body mist" grew 17%. The leaders of the last cycle have stopped growing on Amazon: Sol de Janeiro is down 1% and LUME 7%. Carpe, a sweat-control lotion, grew 46% to $35.8 million.
Hair removal moves home. Hair removal spray search nearly tripled and cream rose 35%, while laser hair removal fell 3%. The cream itself is a low-price race against offshore sellers. The brands with pricing power sell the routine around removal: Bushbalm in about 1,400 Ulta stores and HANNI in every Sephora US door.

Search is running ahead of sales
Over the last twelve months, search for each theme grew 39% to 79% against the twelve before. On the same months a year apart, search grew three to eight times as fast as the sales of the shelves each theme sells on. Shoppers are asking for products the shelf does not yet hold, and that gap is where new brands take share.
Online is where that demand is landing. NIQ puts US body care sold online up 25% over the year to June, against 3% in stores, and scented body care up 13.7% against 5.8% for unscented.
TikTok Shop points the same way. Body care sold about $32 million there in the last 30 days, about $12 million of it medicube's two acid body sets, and #keratosispilaris and #strawberrylegs carry about 4.7 billion views between them. TikTok and Amazon move together; we can't say one causes the other.
Funds are paying about 3x sales
Funds and strategics have done nine body care deals since 2025. TSG bought PHLUR and Saltair within thirteen months, and Advent took a majority stake in Salt & Stone in March. General Atlantic invested in OSEA, Bansk bought BYOMA and Topspin backed Carpe. Funds paid about 3x sales. Strategics paid more: Church & Dwight paid $700 million upfront for Touchland and Unilever reportedly about $1.5 billion for Dr. Squatch.

The same seller keeps showing up. The Center built and sold three body brands since 2023, Naturium, PHLUR and Saltair, and still holds CYKLAR. Yellow Wood has quietly built a mass body business, with Suave in 2023 and Caress and St. Ives through Elida Beauty in 2024. Even the buyers are changing: Dollar Shave Club, now owned by Nexus Capital, bought Truly in September.
Brands to watch, by stage
We checked every body care brand above $5 million on Amazon growing 20% or more, then looked further for smaller brands built on the four themes. We call 30. Each has a real business off Amazon, in stores or its own DTC, and is from North America, Europe or India. Brands owned by a strategic, and brands bought by a fund in the last eighteen months, are left out as benchmarks. We group the calls by Amazon US sales over the last twelve months: early under $2 million, growth $2 million to $10 million, buyout $10 million and up.

Buyout: $10 million and up
eos (scent). $101.7 million on Amazon, up 96%. Founder-owned, in mass retail, and explored a sale in 2024.
Nécessaire (actives). $38.5 million, up 109%. Backed by Cavu and Maveron; Sephora, Nordstrom and Space NK.
Carpe (scent). $35.8 million, up 46%. Sweat-control lotion, held by Topspin since 2024, in Target nationwide.
Tubby Todd (actives). $30.8 million, up 98%. Eczema-prone baby and family skin care, backed by NexPhase Capital since 2022.
goPure (actives). $28.2 million, up 27%. Founder-owned firming creams, about $0.8 million a month on TikTok Shop.
AmLactin (actives). $28.0 million, up 66%. Lactic-acid lotion owned by Advantice Health, a PE-backed consumer health company.
CYKLAR (body wash). $20.5 million, up 595%. At Sephora since 2026; owned by The Center, which has sold three body brands since 2023.
Happy Nuts (scent). $16.9 million, up 16%. Men's whole-body cream; Walmart and DTC, with most sales on Amazon.
Topicals (body wash). $16.5 million, up 27%. Eczema and ingrown-hair treatments at Sephora; about $20 million raised.
DedCool (scent). $11.8 million, up 209%. A fragrance house moving into body, backed by Sandbridge Capital.
OneSkin (actives). $11.4 million, up 105%. Peptide body lotion sold mostly by subscription; Prelude led its 2025 Series A.
Growth: $2 million to $10 million
Crowned Skin (scent). $7.9 million, up 226%. Cologne-scented men's body butter; about $15 million in sales in 2025.
Skinfix (actives). $7.6 million, up 91%. Eczema and bumpy-skin body care from Canada; Stride Consumer holds a minority stake.
Bushbalm (hair removal). $6.2 million, up 88%. Founder-owned, in about 1,400 Ulta stores and 6,000 wax salons.
HUMBLE (scent). $6.0 million, up 28%. Natural deodorant.
HANNI (hair removal). $5.8 million, up 197%. In all of about 600 Sephora US doors; Amazon is about a third of sales.
Cirepil (hair removal). $5.3 million, up 30%. A French salon wax brand moving to home use.
NO HAIR CREW (hair removal). $4.8 million, up 21%. Sold in German drugstores; the one Western brand built on the cream.
Athena Club (hair removal). $3.6 million, up 483%. Razors in about 1,600 Target stores, backed by Cue Ball Capital.
Happy Curves (scent). $3.4 million, up 27%. Women's whole-body deodorant in mass retail.
Almond Clear (body wash). $2.6 million, up 93%. Founder-owned mandelic acid body wash, sold through its own site and Amazon.
Ellis Brooklyn (scent). $2.5 million, up 53%. Sephora, Ulta and Nordstrom, with most of its sales off Amazon.
HUME Supernatural (scent). $2.5 million, up 22%. Deodorant in about 7,000 natural grocery doors.
Chemist at Play (body wash). $2.3 million, up 189%. An Indian brand backed by ICICI Venture, with strong branded search on Amazon.
Early: under $2 million on Amazon
Snif (scent). $1.9 million, up 76%. Reported near $40 million in total sales; VMG Partners invested in 2025.
SUGARDOH (hair removal). $1.2 million, up 21%. Founder-owned sugar wax in about 300 Ulta stores.
Henry Rose (scent). $0.9 million, up 186%. Fragrance and body care in 224 Sephora stores.
Nopalera (scent). $0.5 million, up 154%. Cactus body care in about 150 Costco stores; Amazon is about 6% of sales.
Try Strawberry (actives). $0.5 million, new to Amazon. A bumpy-skin cream built on DTC and paid social.
Soft Services (body wash). $0.2 million, up 99%. Acid body care at Sephora.
Who we left out, and why
Brands owned by a strategic are shown only as context: medicube (APR), Naturium (e.l.f.), Sol de Janeiro (L'Occitane), Native (P&G), Touchland (Church & Dwight), Dr. Squatch (Unilever), and LUME and Flamingo (Harry's). Salt & Stone, Saltair, PHLUR, BYOMA, OSEA and Truly changed hands in the last eighteen months and serve as price benchmarks. Mass brands already held by funds, such as Suave, Caress, Dr Teal's, Hempz and DUDE Wipes, are left out, as are brands that sell mainly on Amazon, brands from outside the regions funds invest in, and brands that have slowed, such as Kopari and Glow Recipe. Strong brands growing outside the four themes, including Every Man Jack, Duke Cannon, Megababe and Loving Tan, are covered in the full report.
What it means
For brands. The shelf is moving toward problems and actives: bumpy skin, eczema, sweat, ingrown hair, dark spots. Brands that name the problem and show what the product does are taking share from older claims like firming. Most of the brands winning built a business in stores or DTC first, then grew on Amazon with demand already in place. Several, including Ellis Brooklyn, Snif and Nopalera, sell far more off Amazon than on it. Whether that is a choice or a gap is worth knowing before a buyer asks.
For investors. Actives on the body and body wash as treatment are the two themes we would spend time on first: the search growth is spread across many terms and the bench of Western independents is thin. Funds are paying about 3x sales and strategics more, which gives a fund buying today a clear set of exit buyers. The next set of names are funded brands with no exit yet, such as OneSkin, Nécessaire, Tubby Todd, Skinfix, Topicals and HANNI, and founder-owned brands that have never sold control, such as Crowned Skin and Bushbalm.
Questions
Which body care trends are growing fastest on Amazon?
Four themes, measured on Amazon US search over the last twelve months against the twelve before: body wash as treatment (acid washes and body toners) up 79%, skincare actives on the body (retinol, urea and body serum) up 72%, hair removal at home (creams and sprays) up 45%, and body care sold as fragrance up 39% without the Salt & Stone brand term. In September, search for each grew three to eight times as fast as the sales of the shelves it sells on.
What are investors paying for body care brands?
Funds have paid about 3x sales: Salt & Stone (Advent, 2026), Saltair (TSG Consumer, 2026) and PHLUR (TSG Consumer, 2025). Strategics have paid 3.4x to 5.5x, including Touchland (Church & Dwight, 2025) at about 5.4x and Dr. Squatch (Unilever, 2025) at about 3.8x.
Which body care brands should investors watch?
We name 30. At buyout size, $10 million and up on Amazon: eos, Nécessaire, Carpe, Tubby Todd, goPure, AmLactin, CYKLAR, Happy Nuts, Topicals, DedCool and OneSkin. At growth size, $2 million to $10 million: Crowned Skin, Skinfix, Bushbalm, HUMBLE, HANNI, Cirepil, NO HAIR CREW, Athena Club, Happy Curves, Almond Clear, Ellis Brooklyn, HUME Supernatural and Chemist at Play. Early, under $2 million: Snif, SUGARDOH, Henry Rose, Nopalera, Try Strawberry and Soft Services.
The full Trend Report 04, with a page on each theme, the deal table with prices and multiples, Amazon's share of sales for each brand and the brands left out, is available to funds through Satin Leaf for investors. Brands can see how we work with brands.
Ransley Carpio
Sources: Amazon US search volume, monthly, October 2024 to September 2026, for the terms that define each theme; theme growth compares the last twelve months with the twelve before, and search against sales compares September 2026 with September 2025 on both. Shelf sales are the Amazon US subcategories each theme sells in, latest month against the same month a year earlier. Brand sales are Amazon US, last twelve months, with growth on the twelve before. TikTok Shop US, last 30 days, to mid-October 2026; TikTok hashtag totals for #keratosispilaris and #strawberrylegs, October 2026. Circana and NIQ market figures, deals, prices and ownership are linked in the text; multiples are price over reported or expected sales at signing. All figures are directional estimates from public sources; no brand supplied data or reviewed this post, and none of the brands named is a Satin Leaf client. This post is general information and is not investment advice. Researched and compiled by Satin Leaf.


Comments